Skip to content
ARBOR Financial Group Home Loans in 48 States

ARBOR Financial Group · NMLS #236669

Government Backed Mortgage

USDA Loans

A USDA loan is a mortgage guaranteed by the U.S. Department of Agriculture that lets eligible buyers purchase a home in qualifying rural and suburban areas with no down payment. With competitive interest rates, flexible credit requirements and reduced mortgage insurance costs, it offers an affordable path to owning a home.

About 3 minutes. Comparing options won't affect your credit score.

Call today: 866-521-6488
Family playing in a sunny field with a wheelbarrow and their dog
Zero down paymentFor eligible rural and suburban homebuyers

USDA Loans at a Glance

0%

Down payment for eligible buyers

115%

Household income limit versus area median

640

Credit score many lenders look for

USDA Loan Basics

Understanding USDA Loans

Man working on a laptop outdoors overlooking green rolling hills

What Are USDA Loans?

USDA loans are government backed mortgages that help low to moderate income borrowers buy homes in eligible rural and suburban areas. They are issued by approved lenders and guaranteed by the U.S. Department of Agriculture, which allows affordable financing with no down payment for buyers who meet the program guidelines.
Couple walking across a sunny lawn toward a white house with a red roof

Who Can Benefit from a USDA Loan?

USDA loans suit first time and repeat buyers who meet the income and location requirements. They are built for individuals and families who want an affordable way to own a home in a rural or suburban community. For guaranteed loans, household income can be up to 115% of the area median income.

Family in cowboy hats running through a meadow below hillside log cabins

How Do USDA Loans Work?

Unlike conventional loans, USDA loans do not require a down payment. You must meet the income limits and buy a home in a USDA eligible area. The program offers fixed rate mortgages with competitive interest rates, and its mortgage insurance costs are typically lower than those on FHA and conventional loans.

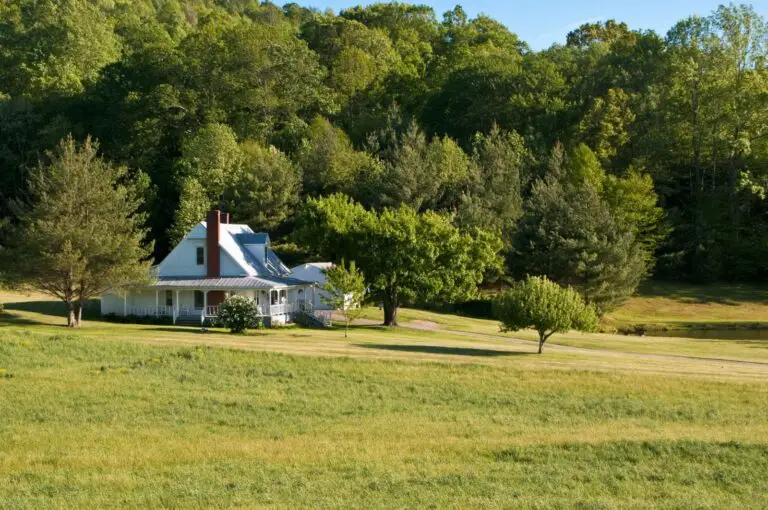
White farmhouse in a wide green meadow surrounded by leafy trees

What Types of USDA Loans Are Available?

There are two main types. USDA Guaranteed Loans are offered through approved lenders, with zero down payment, competitive interest rates and flexible credit requirements. USDA Direct Loans are issued by the USDA itself to very low income borrowers, with subsidized interest rates and flexible repayment terms.

Family walking hand in hand across a hillside field at sunset

What Are the Benefits of a USDA Loan?

USDA loans combine zero down payment with competitive interest rates, reduced mortgage insurance costs and flexible credit requirements. Together, these features make owning a home affordable for buyers in eligible rural and suburban areas, and because no down payment is needed, more of your savings can stay in the bank after closing.

White country cottage with stacked firewood on the porch and mountain views

Is a USDA Loan Right for You?

If you want an affordable home loan with no down payment and you are buying in a USDA eligible area, a USDA loan could be a strong option. Eligibility depends on your household income, your credit and the location of the property, so an ARBOR loan originator can check each one and compare USDA with your other options.

Why ARBOR

Why Choose ARBOR Financial Group for Your USDA Loan

We help homebuyers secure USDA loans with zero down payment, competitive interest rates and flexible credit requirements. Whether you are a first time buyer or simply looking for affordable financing, our USDA loan specialists can guide you through the process.

From prequalification to closing, we offer expert advice and access to USDA approved lenders, so you can find the financing option that fits your home and your budget.

Ready to buy a home with a USDA loan? Contact ARBOR today to explore your eligibility.

Working With ARBOR

  • Access to USDA approved lenders
  • USDA loan specialists to guide you
  • Help for first time and repeat buyers
  • Expert advice from prequalification to closing

Talk with a licensed ARBOR loan originator

866-521-6488

FAQ

USDA Loan FAQs

Answers to common questions about USDA home loans, including eligibility, income limits, credit scores, property rules and the guarantee fee.

Still have questions?

Talk with a licensed ARBOR loan originator about your USDA loan eligibility.

866-521-6488[email protected]Browse all mortgage FAQs
What is a USDA loan?

A USDA loan is a government backed mortgage offered through the U.S. Department of Agriculture. It helps eligible borrowers buy homes in approved rural and suburban areas with affordable financing, no down payment and flexible qualification requirements.

Do USDA loans require a down payment?

In most cases, no. USDA loans offer 100% financing, so eligible borrowers may be able to buy a home with no down payment. You still need to meet the program's income, credit and property eligibility requirements.

Who qualifies for a USDA home loan?

USDA loans are available to eligible borrowers buying a home in a designated rural or suburban area. Qualification is based on household income limits, credit history and your ability to repay the loan under USDA program guidelines.

What credit score do I need for a USDA loan?

Many lenders look for a credit score of around 640 or higher for streamlined USDA approval. Borrowers with lower scores may still qualify, depending on the lender and their overall financial profile.

Are there income limits for USDA loans?

Yes. USDA loans are designed for low to moderate income households, so income limits apply. For guaranteed loans, household income can be up to 115% of the area median income, and the exact limit varies by location and household size.

What types of properties qualify for a USDA loan?

USDA loans are for primary residences in eligible rural or suburban areas. The home must meet USDA property guidelines and typically must be your main home rather than an investment property.

How do I know if a home is in a USDA eligible area?

The U.S. Department of Agriculture publishes an eligibility map that shows which areas qualify for USDA financing. Many suburban and rural communities across the country fall within these approved locations, so it is worth checking before you rule a home out.

Do USDA loans require mortgage insurance?

Yes, in the form of a guarantee fee that works much like mortgage insurance. The program typically charges an upfront fee plus a smaller annual fee that is included in your monthly mortgage payment.

Can I get a USDA loan if I am not a first time buyer?

Yes. USDA loans are open to both first time and repeat buyers, as long as you meet the income limits and buy an eligible home in a qualifying rural or suburban area that will be your primary residence.

What is the difference between USDA guaranteed and direct loans?

Guaranteed loans are made by approved lenders and backed by the USDA, with zero down payment and flexible credit requirements. Direct loans are issued by the USDA itself to very low income borrowers, with subsidized interest rates and flexible repayment terms.

How long does it take to close a USDA loan?

The timeline for a USDA loan closing depends on the lender, your documentation and the USDA approval process, so getting preapproved early can help keep things moving.

Your Path to Homeownership Starts Here

See if a USDA loan fits your plans. Compare your options in a few minutes, or talk with a licensed ARBOR loan originator today.

Comparing options won't affect your credit score.

*Important notice: By refinancing your existing loan, your total finance charges may be higher over the life of the loan. The content provided within this website is presented for information purposes only. This is not a commitment to lend or extend credit. Information and/or dates are subject to change without notice. All loans are subject to credit approval. Other restrictions may apply. ARBOR Financial Group is not affiliated with an agency of the federal government, HUD, FHA or USDA. THIS IS NOT A GOVERNMENT DOCUMENT. HUD, FHA or USDA did not distribute or approve this material.