Skip to content
ARBOR Financial Group Home Loans in 48 States

ARBOR Financial Group · NMLS #236669

Remodel and Build Financing

Renovation and Construction Loans

A renovation or construction loan is a mortgage that finances home improvements, remodeling or a new build, with funds released in stages as the work is completed. These loans cover materials, labor and other construction costs, so you can build from the ground up or upgrade an existing property.

About 3 minutes. Comparing options won't affect your credit score.

Call today: 866-521-6488
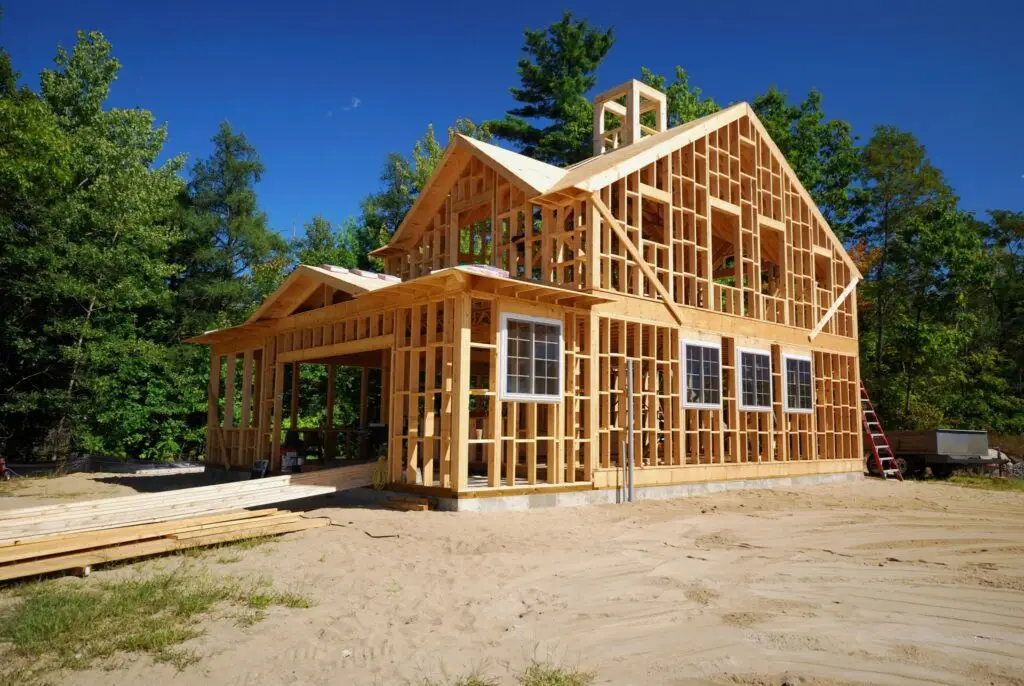
New home under construction with its wood frame in place
Upgrades built into your loanFunds released in stages as work is done

Renovation Loans at a Glance

10 to 20%

Common down payment range

203(k)

FHA renovation loan option

Renovation Basics

Understanding Renovation and Construction Loans

Smiling couple painting a white wall together with paint rollers

What Are Renovation and Construction Loans?

Renovation and construction loans finance the cost of home improvements, remodeling or new home construction. They let homeowners and buyers upgrade, repair or build a property with structured financing that releases funds in stages as work is completed. A renovation loan improves an existing home, while a construction loan builds a new one from the ground up.
Modern bathroom with a double vanity and a glass walk in shower

Who Can Benefit from a Renovation or Construction Loan?

These loans suit buyers purchasing a fixer upper, homeowners planning a remodel and anyone building a custom home. Investors can also use them to rehab properties for resale or rental income. If you are buying a home that needs work, a renovation loan can cover both the purchase price and the cost of repairs in the same loan.

Bright living room with a white sofa and floor to ceiling windows

How Do Renovation and Construction Loans Work?

Unlike a traditional mortgage, these loans release funding in stages rather than as a lump sum. The lender pays out draws as project milestones are completed, so contractors and builders are paid as work progresses. Many lenders require a licensed contractor, whose plans, cost estimates and timeline are reviewed during loan approval.

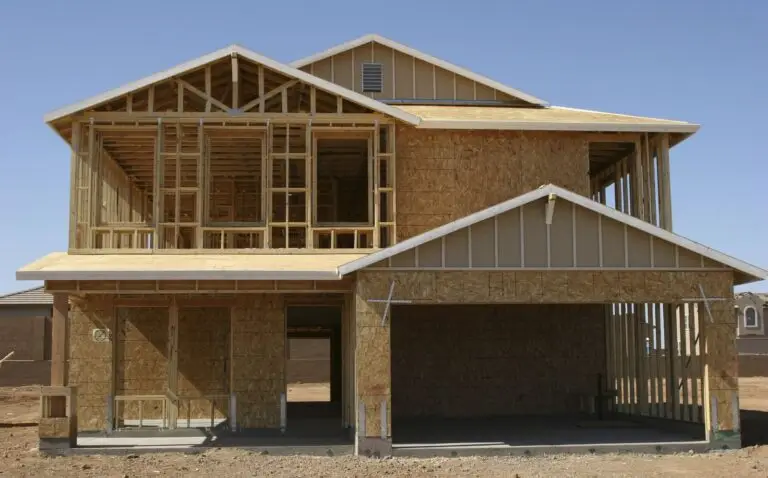
Two story home under construction with framed walls and an open garage

What Types of Renovation and Construction Loans Are Available?

Options include FHA 203(k) renovation loans, Fannie Mae HomeStyle loans, VA renovation loans, construction to permanent loans and standalone construction loans. Each loan type has its own requirements based on the scope of work, your qualifications and the loan terms, so we help you compare them for your project.

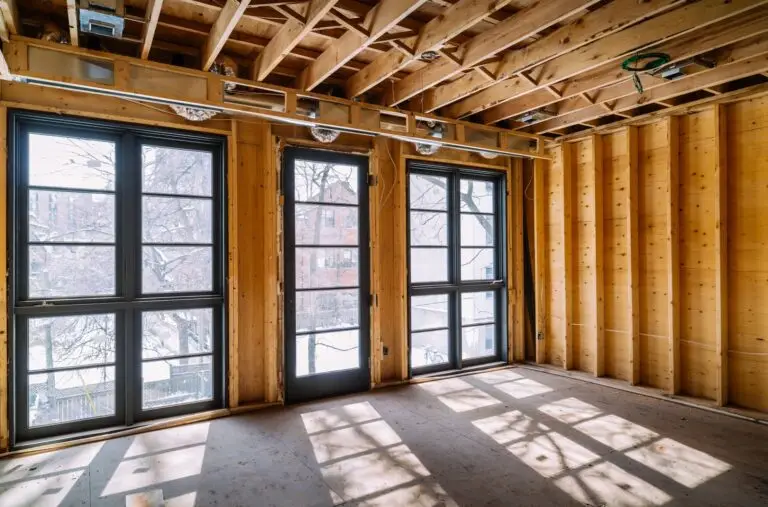
Unfinished interior with exposed wood framing and sunlight through tall windows

What Are the Benefits of a Renovation or Construction Loan?

These loans give you flexible financing for remodeling, home improvements or new construction. You can increase your home's value, customize your living space and spread renovation costs over time instead of paying for everything upfront. Projects such as kitchen and bathroom remodels, roof replacement, flooring upgrades and room additions can all be included.

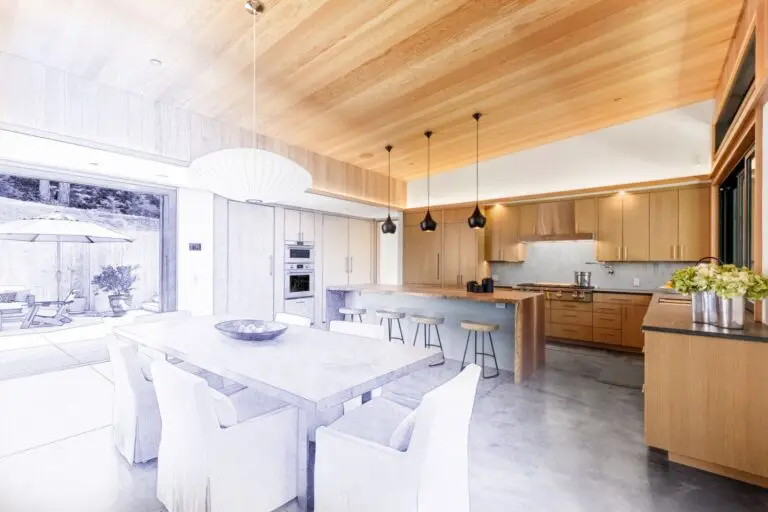
Kitchen and dining area drawn half as a sketch and half finished

Is a Renovation or Construction Loan Right for You?

If you want to upgrade your home, buy a fixer upper or finance a custom built home, a renovation or construction loan may be the right solution. A licensed ARBOR loan originator can review your plans and help you choose the best loan option for your project, from a single room remodel to a new build.

Why ARBOR

Why Choose ARBOR Financial Group for Your Renovation or Construction Loan

We specialize in renovation and construction loan solutions for homeowners, buyers and real estate investors. Whether you want to remodel your home, buy a fixer upper or build a new property, our loan programs offer flexible financing, competitive rates and expert guidance.

From loan application to project completion, our mortgage professionals keep the financing process smooth, working with trusted lenders and approved contractors to bring your plans to life.

Ready to start your project? Talk with ARBOR about renovation and construction financing today.

Working With ARBOR

  • FHA 203(k), HomeStyle and VA renovation options
  • Construction to permanent and standalone loans
  • Financing for homeowners, buyers and investors
  • Guidance from application to project completion

Talk with a licensed ARBOR loan originator

866-521-6488

FAQ

Renovation and Construction Loan FAQs

Answers to common questions about financing a renovation or new build with a single mortgage, including down payments, draws, contractors and closing timelines.

Still have questions?

Talk with a licensed ARBOR loan originator about financing your renovation or construction project.

866-521-6488[email protected]Browse all mortgage FAQs
What is a renovation loan?

A renovation loan lets you finance both the purchase of a home and the cost of repairs or upgrades in a single mortgage. These loans are often used to remodel kitchens, update bathrooms, repair structural issues or improve older homes.

What is the difference between a renovation loan and a construction loan?

A renovation loan finances improvements to an existing home, while a construction loan pays to build a new home from the ground up. Both let you include building or improvement costs within your mortgage financing.

How much do I need to put down on a renovation or construction loan?

Many renovation and construction loans require a down payment of about 10% to 20%, although the exact amount varies by lender, loan type and your qualifications. We confirm your target early so you can plan your project budget with confidence.

Can renovation costs be included in the mortgage?

Yes. Renovation loans let you include the cost of home improvements in your total loan amount, so you can finance repairs, upgrades or remodeling as part of your mortgage instead of paying for them separately.

How are construction loan funds paid out?

Construction loan funds are typically released in stages called draws. The lender pays the builder as construction milestones are completed, which keeps the project moving according to the approved building plan.

Can I buy a fixer upper with a renovation loan?

Yes. Renovation loans are commonly used to buy fixer upper homes. You can finance both the purchase price of the property and the cost of repairs or improvements within the same loan, instead of paying for the work separately.

How long does it take to close a renovation or construction loan?

The time to close a renovation or construction loan depends on the documentation required, construction plans, contractor approvals and underwriting review. Having your plans and contractor estimates ready early helps keep things on schedule.

What types of renovations can be financed?

Renovation loans can finance a wide range of improvements, including structural repairs, kitchen or bathroom remodels, roof replacement, flooring upgrades, room additions and other projects that increase your home's value or livability.

Do I need a licensed contractor for a renovation loan?

In many cases, yes. Many lenders require you to work with a licensed contractor, who provides detailed project plans, cost estimates and timelines that are reviewed during the loan approval process.

Finance Your Remodel or New Build

See which renovation or construction loan fits your project. Compare your options online, or talk with a licensed ARBOR loan originator today.

Comparing options won't affect your credit score.

*Important notice: By refinancing your existing loan, your total finance charges may be higher over the life of the loan. The content provided within this website is presented for information purposes only. This is not a commitment to lend or extend credit. Information and/or dates are subject to change without notice. All loans are subject to credit approval. Other restrictions may apply. ARBOR Financial Group is not affiliated with an agency of the federal government, HUD or FHA. THIS IS NOT A GOVERNMENT DOCUMENT. HUD or FHA did not distribute or approve this material.