Executive Loan Advisor
Megan Doonan, Mortgage Loan Officer Serving Huntington Beach, CA
Finding the right mortgage should feel straightforward. Whether you’re buying, refinancing, or investing, we combine competitive rates with clear, expert guidance to help you move forward with confidence. A smooth, simple, and stress-free path to financing starts here.
Licensed in CA.
NMLS #278387 DRE #01372757 · Company NMLS #236669 · Equal Housing Opportunity · NMLS Consumer Access
About
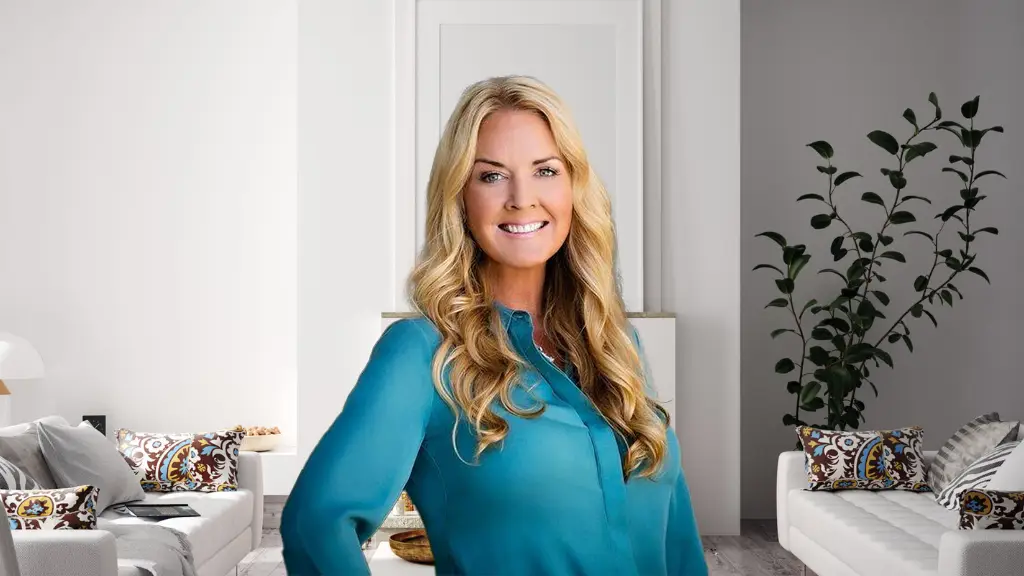
About Megan
Megan Doonan
Start your home loan process here.
With over 25 years of experience in the real estate lending industry, my business has been built on long-term relationships, repeat clients, and referrals; something that reflects the level of care and consistency I bring to every client.
Specializing in tailored mortgage solutions, each loan is structured around the client’s unique financial goals. With access to competitive pricing, a wide range of loan programs, and efficient execution, the loan process is designed to be smooth and straightforward from start to finish.
Whether purchasing, refinancing, or restructuring debt, I look forward to working with you and making your next real estate financing experience a positive one.
Work With Megan
- 949-887-2629
- [email protected]
- Schedule a consultation
- Licensed in CA
- NMLS #278387 DRE #01372757 · Company NMLS #236669
Loan Options
Explore Home Loan Options
Whether you are buying, refinancing or investing, Megan can help you compare the programs that fit your goals.
ARBOR Financial Group
Why Choose ARBOR Financial Group
Whether you are buying your first home, refinancing, or comparing mortgage options, ARBOR Financial Group delivers personalized guidance, competitive rates, and a streamlined lending experience. Backed by an experienced team and proven process, we help you move forward with clarity and confidence from application to closing.
Options across 150+ lenders
Megan compares home loan options across 150+ lenders to find the rate, terms and program that fit your goals.
Licensed in 1 state
Licensed in CA.
Guidance to closing
One point of contact who walks you through each step, from application to closing.
Compare with confidence
Comparing options won't affect your credit score.
FAQ
Mortgage Questions Answered
Clear answers to common home loan and refinance questions. Have another question? Call Megan.
What services do you offer?
We specialize in a wide range of mortgage solutions, including conventional loans, FHA, VA, jumbo loans, and more. Whether you are a first-time homebuyer, self-employed, or looking to refinance, we have tailored options to fit your needs.
How do I get started with a mortgage application?
Getting started is easy. You can reach out to us for a quick strategy session where we’ll discuss your goals and gather some initial details. From there, we guide you through pre-approval, document collection, and the entire loan process step by step.
Am I a strong candidate for a conventional home loan?
Borrowers with stable W2 income, a 620+ credit score, manageable debt, and documented assets are typically strong candidates for conventional financing with competitive rates and flexible terms.
How much down payment do I realistically need to buy a home?
Many qualified buyers purchase with 3% to 5% down on conventional loans or 3.5% down on FHA loans, depending on credit profile and overall financial strength.
Is an FHA loan right for my situation?
FHA loans are often a good fit for first time buyers or borrowers with moderate credit who want lower down payment options and more flexible qualification guidelines.
How do lenders evaluate self employed income?
Lenders typically average the last two years of net income shown on tax returns. Consistent earnings, organized financials, and stable business history strengthen approval.
Can I qualify if I own a business or receive 1099 income?
Yes. Self employed and 1099 borrowers can qualify with proper documentation, steady income history, and strong credit. Clean records help ensure smoother underwriting.
What makes an investment property loan approval strong?
Strong investor files usually include solid credit, adequate reserves, rental income support, and appropriate down payment, typically 15% to 25% depending on loan structure.
When does refinancing make financial sense?
Refinancing may make sense when you can lower your interest rate, reduce your monthly payment, shorten your loan term, or improve overall financial positioning.
What is the first step to get started?
The first step is a mortgage pre approval. This includes reviewing income, credit, and assets to determine eligibility and provide a clear purchase or refinance strategy.
Ready to Get Started With Megan?
Talk through your goals and compare your options with a licensed loan originator.
Comparing options won't affect your credit score.